Truck Financing Bad Credit Options for Used Truck Buyers
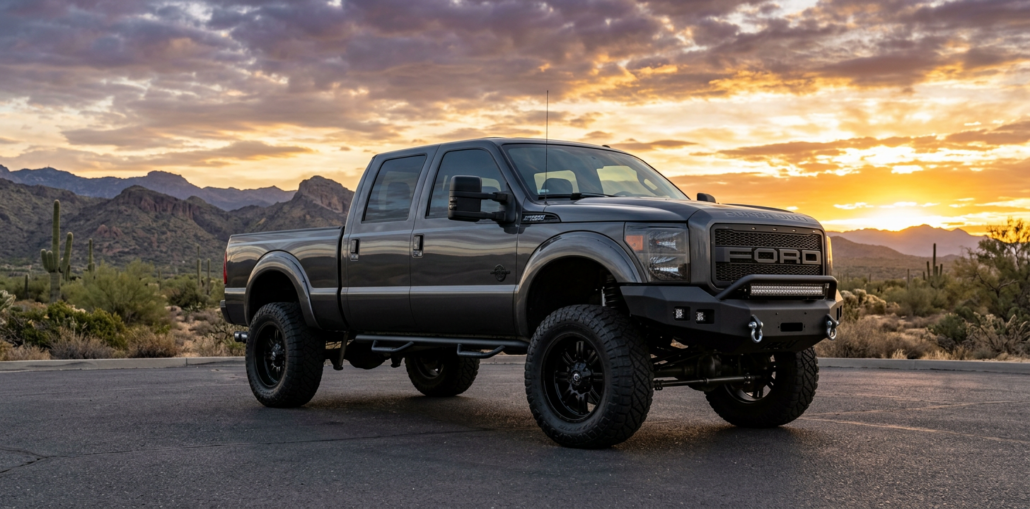
A credit challenge doesn’t automatically take you out of the market for a dependable pickup. The key is to shop with a realistic payment target, understand the full loan cost, and choose a truck that works for both your daily needs and your budget.
For buyers comparing heavy-duty pickups, truck financing bad credit options can include dealership-arranged lending, a bank or credit-union preapproval, a qualified co-buyer, a larger down payment, and trade-in equity. Approval is never guaranteed, but preparation can give lenders a clearer picture of your income, stability, and ability to repay.
Used-vehicle financing remains a major part of the market. Experian reported that the average used-vehicle loan amount was $27,528 in the fourth quarter of 2025, with an average monthly payment of $537. That is a useful reminder to focus on the complete payment, loan term, and amount financed, not just the truck’s advertised price. (experian.com)
Bad Credit Truck Financing Options at a Glance
| Financing path | Best fit | Main benefit | Important consideration |
|---|---|---|---|
| Dealership-arranged financing | Buyers wanting vehicle and loan help together | Access to multiple lender programs | Compare the full terms carefully |
| Bank or credit union | Buyers with an existing relationship or preapproval | May offer competitive terms | Approval criteria can be tighter |
| Co-buyer application | Buyers with a qualified co-buyer | Can strengthen the application | Both parties share responsibility |
| Larger down payment | Buyers with available cash or equity | Reduces the amount borrowed | Keep emergency savings intact |
| Trade-in | Buyers replacing a current vehicle | Can add equity toward the deal | Confirm payoff and market value |
What Lenders Usually Review Before Approving a Truck Loan
Credit score matters, but it is only one part of an auto-loan decision. Lenders commonly review your income, employment history, housing payment, debt obligations, down payment, requested loan amount, and the specific truck being financed.
A well-kept used Ford F-250, Ram 2500, Chevrolet Silverado 2500HD, GMC Sierra 2500HD, or work-ready half-ton can be a practical choice when it matches the lender’s guidelines and your actual payment comfort level. We recommend starting with the job the truck needs to do. If you do not tow heavy trailers or haul commercial loads, a capable gas truck may provide a lower purchase price and a more manageable financing amount than a diesel heavy-duty pickup.
Stable income and residence history can help
Bring clear, current documentation when requested. Pay stubs, bank statements, proof of address, a valid driver’s license, and insurance information can help the application move forward without delays. Self-employed buyers may need additional income documentation, such as tax returns or recent bank statements.
The amount financed matters as much as the truck price
Taxes, registration, warranty products, negative equity from a prior loan, and optional accessories can all affect the final amount financed. Ask to review the purchase order and lending disclosures line by line before signing. The annual percentage rate, finance charge, total of payments, and loan length should all be clear.
How to Improve Your Bad Credit Truck Financing Options
You do not need to wait for perfect credit before exploring a truck purchase. However, taking a few practical steps can improve the choices available to you and reduce surprises during the buying process.
Know your credit report before applying
Review your credit reports for inaccurate late payments, accounts that do not belong to you, or outdated balances. Correcting legitimate errors may help your profile, and it gives you a better understanding of what a lender may see.
Set a payment ceiling before choosing a truck
Start with a monthly payment that leaves room for fuel, insurance, maintenance, registration, and work-related expenses. A longer term can lower the monthly payment, but it can also increase the interest paid over the life of the loan and keep you in the loan longer than expected.
Use a down payment strategically
A down payment lowers the amount borrowed and can reduce the lender’s risk. Even a modest amount may help, especially when paired with steady verifiable income. Do not drain every dollar in savings, though. Truck ownership is easier when you retain a financial cushion for tires, service, and unexpected repairs.
Consider a trade-in, but understand the payoff
A trade-in can serve as part of your down payment if its value exceeds the loan payoff. If you owe more than the vehicle is worth, that negative equity may be added to the next loan, increasing the amount financed. Get a clear appraisal and payoff estimate before assuming your current vehicle will lower the payment.
You can start with a no-pressure estimate through Sell or Trade Your Vehicle. Knowing the numbers early helps you compare trucks honestly and avoid building a deal around guesswork.
Keep loan shopping within a focused window
Comparing offers is smart. The Consumer Financial Protection Bureau explains that auto-loan inquiries made within a 14-to-45-day period generally count as one inquiry for scoring purposes. That gives buyers a practical window to evaluate bank, credit-union, and dealership financing offers without stretching the process over several months. (consumerfinance.gov)
Choosing the Right Truck for Your Approval and Your Work
The best financed truck is not always the biggest truck on the lot. It is the one that handles your towing, hauling, jobsite, family, or recreational needs without forcing you into a payment that becomes difficult to maintain.
When a diesel truck makes sense
Diesel trucks are popular for frequent towing, heavy payloads, fifth-wheel trailers, and long highway miles. A used Power Stroke, Cummins, or Duramax truck can be an outstanding workhorse, but buyers should budget for its higher purchase price, fuel costs, insurance, and maintenance needs.
If you genuinely need heavy-duty capability, browse Diesel Trucks and compare cab configuration, bed length, drivetrain, towing equipment, mileage, and condition. A properly equipped F-250, F-350, Silverado 2500HD, Sierra 2500HD, Ram 2500, or Ram 3500 should fit the work rather than simply look the part.
When a gas truck may be the stronger financial fit
A gas-powered truck can be a better value for buyers who tow occasionally, commute regularly, or need a dependable pickup for lighter work. The lower entry price can reduce the financed balance, which may create a more comfortable payment and a faster path toward refinancing later if your credit improves.
Lifted trucks require a full-budget view
Custom lifted trucks offer impressive road presence and off-road capability, but buyers should account for tire replacement costs, ride preferences, insurance, parking needs, and any trailer setup requirements. A quality build should have documented components and should be evaluated for how it will serve your daily driving and work needs.
For buyers who want that style without compromising their buying plan, explore Lifted Trucks that match your budget range before applying for a specific vehicle.
Financing Paths to Treat Carefully
Buy-here-pay-here and no-credit-check offers may seem like the fastest answer when credit is limited. They can be an option for some buyers, but the Consumer Financial Protection Bureau warns that these loans often carry higher interest rates than bank, credit-union, or other lender financing. The agency also notes that some providers may report negative payment activity without reporting on-time payments, so ask in writing whether on-time payments are reported to the credit bureaus. (consumerfinance.gov)
We encourage buyers to compare any offer by its APR, payment, term, total amount paid, prepayment policy, and required insurance or tracking-device terms. A low payment is not automatically a good deal if it comes from a very long term or a high-rate loan.
A Straightforward Plan Before You Apply
- Decide how you will use the truck, including towing, payload, daily miles, and passenger needs.
- Establish a realistic down payment and monthly payment range.
- Gather proof of income, residence, insurance, and your trade payoff if applicable.
- Review your credit reports and correct errors before submitting applications.
- Compare the full cost of at least a few financing paths within a focused time frame.
- Choose a truck based on capability, condition, and total ownership cost, not only its monthly payment.
At Unique Trucks, our family-owned Scottsdale dealership has more than 20 years of experience helping buyers explore financing for pre-owned diesel trucks, lifted trucks, work trucks, heavy-duty pickups, and SUVs. We can help you review available options while you shop a truck that fits the work you need it to do.
Explore Your Financing Options With Confidence
Ready to take the next step? Start with Get Pre-Qualified to review personalized financing options, then View Current Inventory to compare available trucks. If you are ready for a full application, you can also Complete a Credit Application or call (480) 210-2660 to speak with the Unique Trucks Team.
We serve buyers throughout Scottsdale, Phoenix, Arizona, and nationwide with a no-pressure approach. Bring your questions, your trade details, and the kind of truck you need. We will help you work through the options clearly.
Frequently Asked Questions About Bad Credit Truck Financing
Can I finance a truck with bad credit?
Yes, many buyers with challenged credit can qualify for some type of truck financing, although approval, rate, down payment, and terms depend on the full application. Stable income, a manageable amount financed, a trade-in, or a down payment can improve the strength of an application.
Does getting pre-qualified hurt my credit?
It depends on the lender and the type of pre-qualification. At Unique Trucks, the online pre-qualification page states that its Capital One form lets buyers view personalized financing options with no impact to their credit score. Review the disclosure on any form before submitting personal information. (uniquetrucks.com)
Is a co-buyer the same as a co-signer?
The terms are often used similarly in vehicle financing, but the exact structure can differ by lender. In either case, the additional applicant’s credit and income may support the application, and both people can be responsible for the loan. Confirm the lender’s obligations before moving forward.
How much should I put down on a used truck with bad credit?
There is no single required amount. More money down can lower the loan amount and may improve approval odds, but the right amount should not leave you without emergency savings. A trade-in with positive equity may also serve as a down payment.
Can I refinance my truck loan later?
Possibly. If you make on-time payments, reduce the loan balance, and improve your credit profile, refinancing may become available through a bank, credit union, or other lender. Compare the new APR, term, fees, and total cost before refinancing.
Should I choose a diesel truck or a gas truck if my credit is challenged?
Choose based on actual use and total cost. A diesel heavy-duty truck can be worth it for frequent heavy towing and commercial demands, while a gas truck may lower the purchase price and financed balance for buyers with lighter-duty needs. The right answer is the truck that meets your workload without putting unnecessary pressure on your budget.
The Bottom Line
Bad credit can narrow your financing choices, but it does not mean you have to accept the first offer or buy more truck than your budget supports. Focus on the total loan cost, provide accurate documentation, compare financing paths, and choose a capable used truck that fits your real work and driving needs.
A dependable pickup should move your plans forward, whether that means a work-ready Ram, a towing-focused Ford Super Duty, a Duramax-powered Chevrolet or GMC, or a practical gas truck. With the right preparation, you can approach the process informed, organized, and ready to make a confident decision.
About Unique Trucks
Unique Trucks is a family-owned dealership with over 20 years of experience serving truck buyers from Scottsdale, Phoenix, throughout Arizona, and across the United States. The dealership specializes in quality pre-owned lifted trucks, diesel trucks, work trucks, heavy-duty pickups, custom builds, and used SUVs.
The Unique Trucks Team offers competitive financing, trade-ins, vehicle sourcing, and nationwide shipping to help customers find the right truck with a no-pressure buying experience.
Browse the current inventory, get pre-qualified, or call (480) 210-2660 to speak with the Unique Trucks Team today.